How Much Does Life Insurance Cost in Australia?
In Australia, no single price determines how much a life insurance policy will cost. What you pay depends on your circumstances, how much cover you need and the policy you choose. Two people looking for the same amount of cover can still be quoted very different premiums based on their individual circumstances. Your age, health, smoking status, occupation and lifestyle can all affect the price. The way your premiums are structured can make a difference too.
That’s why average costs you see online only tell part of the story. What matters is what the right level of cover will cost you, and what those premiums could look like over the time of your policy.
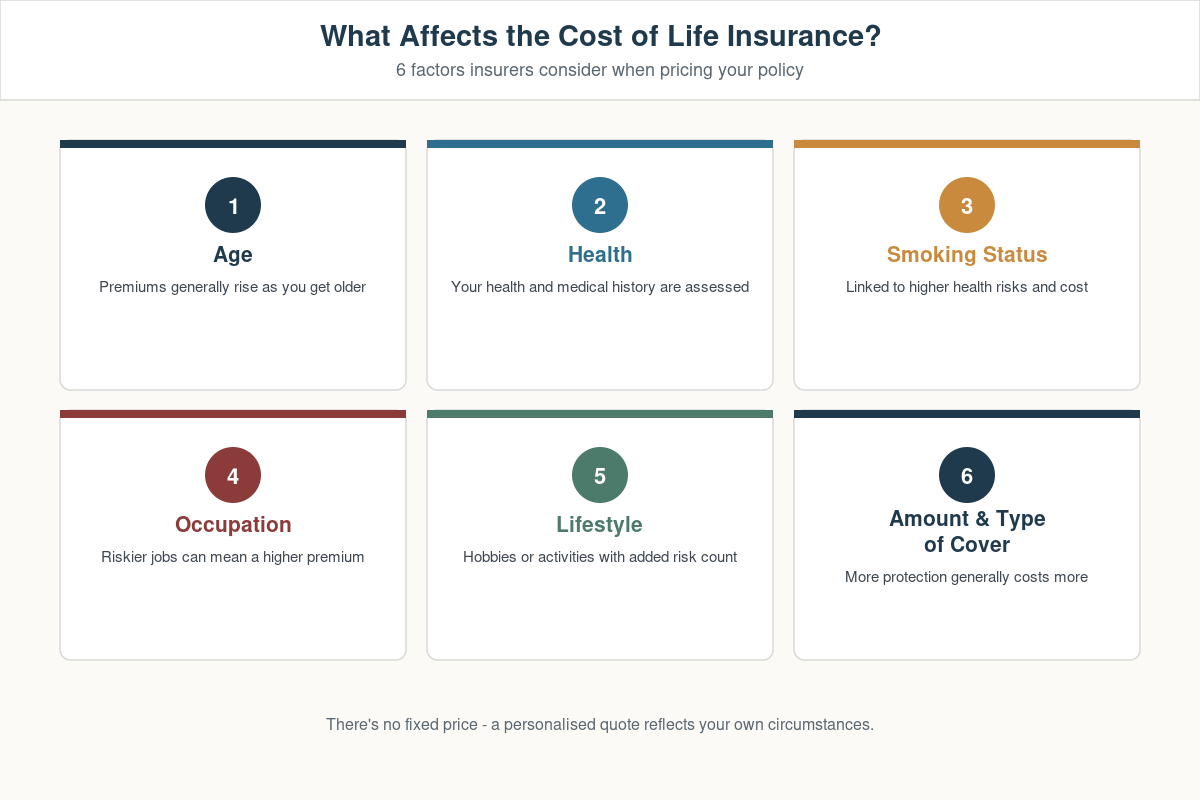
What Factors Affect Life Insurance Premiums?
When you apply for life insurance, an insurer considers a range of factors when working out your premium.
Age
Generally, life insurance premiums tend to increase as you get older, as the likelihood of a claim can increase with age.
Health
Your current health and medical history can play a role in assessing your application and determining your premium.
Smoking status
If you smoke, this can affect your premium because of the health risks associated with smoking.
Occupation
Some jobs involve greater levels of risk than others. The nature of your work may therefore be considered when determining your premium.
Lifestyle
Certain lifestyle factors, including activities or hobbies that carry additional risks, may also be taken into account.
Amount and type of cover
The amount of protection you choose can affect your policy cost. The types of risks you want to cover can also influence your premium.
While these factors are generalised, insurers will consider them alongside your individual circumstances, providing a premium that reflects your situation.
How Does the Amount of Cover Affect the Cost?
Typically, a higher level of cover means paying a higher premium, as you’re asking the insurer to provide a greater financial benefit if a claim is made. But before comparing prices, consider: how much cover do you actually need?
A lower level of cover may make the premium more affordable, but it may not provide enough to support your family, address outstanding debts or meet the other financial needs you’re trying to protect against. The aim is to find a level of cover that provides meaningful financial support while still fitting within your budget.
Stepped vs Other Premium Structures: What Should You Know?
Life insurance premiums can be structured in different ways. Some policies start with a lower premium that generally increases as you get older. Others may cost more upfront but can follow a different pricing path over time.
You may hear these called Variable Age-Stepped Premiums and Variable Premiums. The key point is that the cheapest option today may not be the best value over the years you hold the policy.
Premiums can also change over time, so it helps to look beyond the starting price and understand how the policy is structured before deciding.
Is Cheaper Life Insurance Always Better?
When choosing a life insurance policy, it’s important to understand how it fits into your budget, especially if you expect to keep it for a long time. But that does not mean the cheapest option is always the best.
Two policies can have similar premiums but differ in level of cover, policy definitions, inclusions, exclusions, features and overall flexibility. A cheaper policy may also offer less than what you actually need.
That’s why it’s important to look under the hood of your policy and consider what you’re getting back for your hard-earned money. There’s not a great deal of value in choosing a cheaper policy if it doesn’t provide the protection you need.
The most sustainable policy provides the right protection for your circumstances while remaining affordable enough to maintain. Carefully comparing your options and seeking professional advice where relevant can help you make an informed decision.
Getting a Life Insurance Quote That Reflects Your Needs
How much will your life insurance actually cost? The answer depends on your circumstances and the cover amount you need. Rather than relying on generic online estimates, a personalised quote can incorporate the factors listed and provide a figure you can work with.
A quote can give you a clearer idea of what you may pay, but it’s also important to know whether the cover is suitable for your needs and financial situation.
At Panorama Financial Services, we can help you understand your options, compare policies and premiums across insurers, and work out what type and level of cover may suit your circumstances.
It’s About Finding the Right Balance
As stated, there is no fixed price for a life insurance policy, and the cheapest one does not always fit the best. The right approach is to consider how much protection you need, what fits your budget, and whether the policy includes the features that matter to you.
If you’re considering life insurance or reviewing your existing cover, get in touch with the Panorama team to talk through your options.
Frequently asked questions
Explore the answers to some common questions about the cost of Life Insurance.
There’s no standard monthly price for life insurance. Your premium will depend on factors such as your age, health, lifestyle, occupation, the amount of cover you choose and the type of policy. The best way to understand what you might pay is to get a personalised quote based on your circumstances.
Several factors can affect the cost of life insurance, including your age, health, smoking status, occupation, lifestyle and the amount of cover you need. The type of cover and how your premiums are structured can also make a difference.
Generally, yes. As you get older, life insurance can become more expensive because age is one of the factors insurers consider when calculating premiums. However, the exact cost will depend on your individual circumstances and the policy you choose.
The easiest way is to get a personalised quote. An insurer or financial adviser can look at your circumstances, the level of cover you need and the type of policy you’re considering to give you a clearer idea of the cost. It’s also worth looking beyond the premium to make sure the cover suits your needs.

Calendar
We’re here to help you protect what matters most.
Whether you’re planning for your family, your future, or your business, our team listens, simplifies, and guides you every step of the way.
Reach out and let’s build your peace of mind together.